

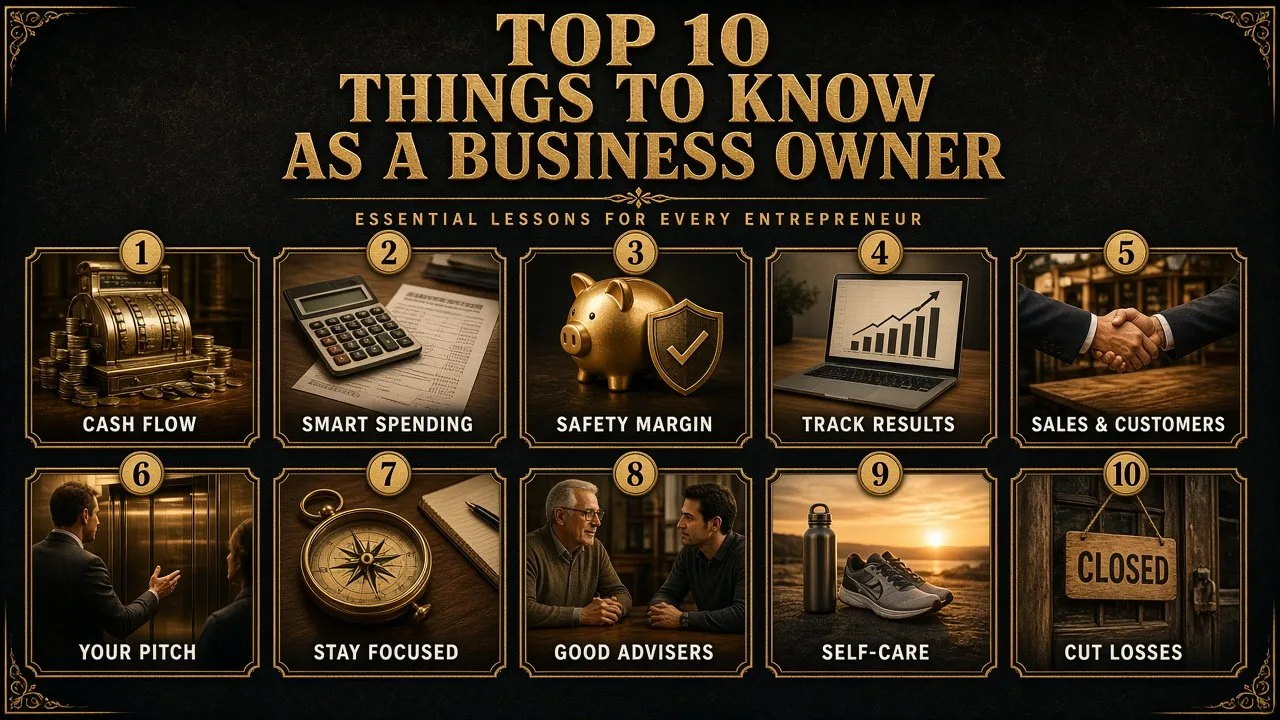
Things to know as a business owner start with cash flow, cost control and clear numbers, then cover selling, focus, mentors, your health and when to quit.
Running your own business is one of the most rewarding paths in working life, and also one of the most demanding. Small firms are the backbone of many economies. In the United States alone, the SBA Office of Advocacy counts more than 34.7 million small businesses, which make up 99.9 percent of all firms and employ about 45.9 percent of American workers. Yet the same office reports that only around half of new employer establishments are still operating five years after they open.
The gap between businesses that last and those that close is rarely about one big idea. It usually comes down to a handful of habits: how the owner handles money, how they find and keep customers, how they spend their own time and energy, and how honestly they read the signals their business sends. This guide covers the ten most essential things every business owner should know, with practical steps, real data and a few lessons from history.
How We Chose These 10 Essentials
This is an editorial list, not a scientific ranking. Each lesson was chosen because it is supported by official small business guidance, published survival data or well-known research on decision making, and because it applies to almost any kind of business, from a one-person consultancy to a shop with a dozen staff. The list starts with money, because money problems end more businesses than anything else, then moves to customers, focus and people, and ends with the owner's own wellbeing and judgement.
Figures quoted here are mostly from the United States, because US agencies publish the most detailed long-run data on business survival. The principles, however, apply to owners everywhere.
Things to Know as a Business Owner at a Glance
| No. | Essential | Why It Matters | Key Fact |
|---|---|---|---|
| 1 | Cash flow is not profit | A profitable business can still run out of cash | Running out of capital was cited in 70 percent of 431 recent VC-backed shutdowns studied by CB Insights |
| 2 | Every expense needs a job | Small leaks add up in the early years | SBA guidance says to count at least one year of monthly expenses before launch |
| 3 | Build in a safety margin | Costs tend to run higher and sales slower than planned | The SBA suggests adding about 10 percent to cover expenses you cannot predict |
| 4 | Measure what matters | You cannot fix what you do not track | The break-even point equals fixed costs divided by price minus variable cost |
| 5 | Customers come first | Without demand, nothing else works | Poor product-market fit was cited in 43 percent of the CB Insights shutdowns |
| 6 | Always be ready to pitch | Opportunities appear without warning | A clear pitch can be delivered in under a minute |
| 7 | Focus beats busyness | Time and attention are limited | Saying no protects the core business |
| 8 | Find good advisers | No owner knows everything | SCORE has offered free US business mentoring since 1964 |
| 9 | Your health is a business asset | A burned-out owner makes poor decisions | The WHO recognised burnout as an occupational phenomenon in 2019 |
| 10 | Know when to cut your losses | Past spending should not dictate future choices | The sunk cost effect was documented by Arkes and Blumer in 1985 |
1. Cash Flow Is Not the Same as Profit
| Attribute | Details |
|---|---|
| Core idea | Cash in the bank pays the bills, not profit on paper |
| Common trap | Strong sales, but customers pay late while bills arrive on time |
| Key tools | A monthly cash flow forecast and an up-to-date list of who owes you money |
| Quick wins | Deposits, upfront payments, shorter payment terms and memberships |
| Warning sign | Regularly using personal savings or credit to cover routine bills |
What It Means
Profit is what is left after you subtract costs from revenue over a period. Cash flow is the timing of money actually coming in and going out. The two can look very different. A business can win a large order, record a healthy profit for the month and still be unable to pay rent, because the customer will not pay for sixty days while suppliers and staff need paying now.
This is why so many owners are caught off guard. When CB Insights studied the post-mortems of 431 venture-backed startups that shut down from 2023 onwards, running out of capital was cited in 70 percent of cases. The analysts noted that a lack of cash is usually the final cause of death rather than the root problem, but it is the point where every other weakness becomes fatal.
How to Improve It
- Ask for a deposit or partial payment upfront, especially for custom work, service projects and high-value products.
- Invoice promptly and make paying easy, with clear due dates and several payment options.
- Offer a modest discount for early payment if your margins allow it.
- Consider a membership, subscription or retainer model that brings in predictable monthly income.
- Negotiate longer payment terms with suppliers where you can, so money goes out closer to when it comes in.
- Keep a cash buffer for slow months rather than spending every surplus.
Why It Matters
Cash is the oxygen of a business. An owner who forecasts cash a few months ahead can spot a shortfall early and act, by chasing invoices, delaying a purchase or arranging a line of credit before it becomes urgent. An owner who only looks at last month's profit often discovers the problem when the account is already empty.
Interesting Facts
- Accountants describe the gap between paying suppliers and collecting from customers as the cash conversion cycle.
- Fast-growing businesses are especially exposed, because growth usually means buying stock and hiring before the extra sales are paid for.
- Many lenders look at cash flow statements as closely as profit figures when deciding whether to lend.
2. Every Expense Needs a Job
| Attribute | Details |
|---|---|
| Core idea | Spend deliberately, especially in the first years |
| Typical startup costs | Premises, equipment, licences, insurance, a lawyer and accountant, inventory, salaries, marketing and a website, as listed by the SBA |
| Planning rule | Separate one-time costs from monthly costs |
| Planning horizon | At least one year of monthly expenses, ideally five, according to SBA guidance |
| Mindset | Every cost should help you earn, save or protect money |
What It Means
Even owners who start with a comfortable cushion of savings cannot know exactly how long it will take to reach their revenue goals. Watching every outgoing payment is not about being mean. It is about making sure each expense earns its place. A new office, a premium software plan or a branded van might feel like signs of success, but if they do not help the business win or serve customers, they quietly shorten your runway.
The US Small Business Administration advises new owners to list their startup expenses in two groups. One-time costs include major equipment, logo design, permits and licences. Monthly costs include rent, salaries and utilities. Adding them up shows how much capital you need and, just as importantly, when you will need it.
Practical Habits
- Review every subscription and recurring charge at least once a quarter and cancel what you no longer use.
- Get more than one quote for significant purchases.
- Lease or buy second-hand equipment while demand is still uncertain.
- Keep business and personal finances in separate accounts so you can see exactly where money goes.
- Ask a simple question before each purchase: will this help us sell more, serve customers better or reduce another cost?
Why It Matters
Careful spending buys time, and time is what a young business needs most to find its customers and refine its offer. The SBA also points out that tracking expenses properly helps at tax time, because many startup and running costs are deductible.
Interesting Facts
- The term bootstrapping, used for self-funded businesses, comes from the old phrase about pulling yourself up by your own bootstraps.
- Self-funding keeps full control in the owner's hands, but the SBA warns that it also means taking on all the risk personally.
- Many successful companies, from small family firms to global brands, began in garages, spare rooms and kitchens to keep costs low.
3. Always Build In a Financial Safety Margin
| Attribute | Details |
|---|---|
| Core idea | Plan for costs to be higher and revenue to be lower than you hope |
| SBA tip | Add roughly 10 percent to your break-even analysis for unpredictable expenses |
| Useful method | Prepare best case, expected case and worst case forecasts |
| Who checks it | Lenders and investors compare your expected costs with projected revenue |
| Goal | Stay afloat even if growth is slower than planned |
What It Means
Almost every new owner is optimistic, and that optimism is part of what makes people start businesses in the first place. The danger is building a financial plan that only works if everything goes right. A sensible rule is to overestimate expenses and underestimate revenue. You should still aim high and chase ambitious sales targets, but spend as though those targets might take longer to reach.
In its guidance on break-even analysis, the SBA suggests adding a little extra, such as 10 percent, to cover miscellaneous expenses that cannot be predicted. Unexpected repairs, price rises from suppliers, slower-paying customers and seasonal dips all eat into the margin you thought you had.
How to Plan With Leeway
- Build three versions of your forecast: a best case, an expected case and a worst case.
- Make sure the business can survive the worst case for at least several months.
- Keep a separate emergency fund that you only touch for genuine surprises.
- Arrange financing options, such as an overdraft or line of credit, before you need them, when lenders see you as a lower risk.
- Revisit your forecast every month and update it with real figures.
Why It Matters
Survival data shows how important resilience is. According to the SBA Office of Advocacy, an average of 67.9 percent of new US employer establishments survived at least two years between 1994 and 2021, while the five-year survival rate was 49.2 percent and the ten-year rate was 33.8 percent. The good news is that survival odds improve with age: more than two-thirds of establishments that reach five years go on to reach ten. A financial safety margin is what carries a business through those vulnerable early years.
Interesting Facts
- US Bureau of Labor Statistics data shows that one-year survival rates dipped for businesses born in recession years such as 2001 and 2008.
- Of US establishments born in 2022, 77.6 percent survived their first year, according to the BLS.
- The SBA Office of Advocacy found that 76.5 percent of establishments that reach ten years also reach fifteen.
4. Measure What Matters and Track Your Results
| Attribute | Details |
|---|---|
| Core idea | Decide using data, not gut feeling alone |
| Essential number | Your break-even point |
| Break-even formula | Fixed costs divided by (price per unit minus variable cost per unit) |
| Common measures | Revenue, gross margin, cash balance, customer acquisition cost, repeat purchase rate |
| Review rhythm | Weekly for key figures, monthly for full financial statements |
What It Means
Tracking and measuring results is the only reliable way to know whether your products, prices, marketing and processes are working. Without numbers, owners tend to keep spending on things that feel productive but do not pay off, and they may abandon ideas that were actually working.
The most important number for any new business is its break-even point, where total revenue equals total costs. The SBA explains it with a simple formula: fixed costs divided by the difference between the selling price and the variable cost of each unit. If your monthly fixed costs are 5,000 and each sale earns you 25 after variable costs, you need 200 sales a month just to break even.
What to Track
- Sales and revenue, by product, service and channel.
- Gross margin, so you know which offers actually make money.
- Cash in the bank and money owed to you.
- The cost of winning a new customer, compared with how much a typical customer spends over time.
- Repeat business and customer satisfaction.
- Results of each marketing campaign, so you can put more money behind what works.
Why It Matters
Good measurement turns a business from guesswork into a series of small experiments. You try something, check the results, keep what works and drop what does not. The SBA notes that a break-even analysis also helps limit decisions made on emotion, which is useful when you are deeply attached to your own idea.
Interesting Facts
- Simple tools such as a spreadsheet or basic accounting software are enough for most small businesses to start tracking key figures.
- Investors usually ask for income statements, balance sheets and cash flow statements, plus forecasts that are monthly or quarterly for the first year.
- Many owners set up a one-page dashboard with five to ten numbers they check every week.
5. Sales and Customers Keep the Lights On
| Attribute | Details |
|---|---|
| Core idea | A business exists to find, win and keep customers |
| First question | Is there real demand for what you sell? |
| SBA market questions | Demand, market size, economic indicators, location, saturation and pricing |
| Biggest risk | Building something people do not want enough to pay for |
| Focus | Revenue first, brand building alongside it |
What It Means
Sales are the lifeblood of any business. Before worrying about a perfect logo or a famous brand, owners need a dependable system for generating leads and turning them into paying customers. Brand reputation tends to grow over time as a result of good service, consistent quality and happy customers talking about you.
The most basic test is whether enough people want what you offer at a price that makes you a profit. In the CB Insights analysis of recent startup failures, poor product-market fit was cited in 43 percent of cases, the most common root cause after running out of money. The SBA recommends market research before launch, asking about demand, the size of the market, where customers live, how many competitors already exist and what people currently pay for alternatives.
Building a Sales and Marketing System
- Define your ideal customer as precisely as you can, including their problems and where they look for solutions.
- Talk to real customers early, through interviews, surveys or simple conversations.
- Choose a small number of marketing channels and do them well, rather than trying everything at once.
- Create a clear process that moves a lead from first contact to purchase.
- Ask happy customers for reviews and referrals.
- Hire or partner with experienced people for marketing once you can afford it.
Why It Matters
Every other lesson in this list depends on revenue. Cash flow, safety margins and growth plans only work if customers keep buying. A business with average systems but strong demand can usually fix its problems. A business with excellent systems but no real demand rarely survives.
Interesting Facts
- Keeping an existing customer is generally cheaper than winning a new one, which is why repeat business is so valuable.
- The SBA lists surveys, questionnaires, focus groups and in-depth interviews as direct market research methods.
- Competitive analysis helps you find your window of opportunity and the barriers you may face entering a market.
6. Be Ready to Pitch Your Business at Any Moment
| Attribute | Details |
|---|---|
| Core idea | Anyone you meet could become a customer, partner or investor |
| Format | A short spoken summary, often called an elevator pitch |
| Ideal length | About 30 to 60 seconds |
| Key content | The problem you solve, who you serve, what makes you different and a clear next step |
| Practice | Rehearse until it sounds natural, not memorised |
What It Means
As a business owner, you are your company's first and most important salesperson. Opportunities do not always arrive at networking events or scheduled meetings. They can come from a conversation on a train, at a family wedding or in a queue at the bank. Having a brief, clear pitch ready means you never miss the chance to start a relationship that could matter.
A good pitch is not a hard sell. It explains in plain words what problem you solve, who you help, why your approach is different and what the listener could do next, such as visiting your shop, booking a call or trying a sample.
How to Build Your Pitch
- Start with the problem your customers face, not with your company history.
- Explain your solution in one or two simple sentences without jargon.
- Mention one strong proof point, such as a result you achieved for a customer.
- End with an easy next step.
- Prepare short versions for different listeners, such as customers, suppliers and investors.
Why It Matters
A clear pitch also sharpens your own thinking. If you cannot explain your business simply, customers will struggle to understand it too. Many owners find that refining their pitch helps them refine their offer, their marketing message and even their website.
Interesting Facts
- The name elevator pitch comes from the idea of explaining your business in the time it takes to ride a lift with someone.
- The SBA advises that a business plan's executive summary should briefly say what the company is and why it will succeed, much like a written pitch.
- Pitch competitions for startups are now held by universities, governments and private investors around the world.
7. Stay Focused on Your Core Business
| Attribute | Details |
|---|---|
| Core idea | Your time and attention are your scarcest resources |
| Common trap | Taking on side projects and favours that pull you away from the main business |
| Useful habit | Set a few clear priorities each week and month |
| Key skill | Saying no politely but firmly |
| Result | Faster progress on what actually grows the business |
What It Means
Once people know you run a business, you will be asked to join projects, offer advice, sit on committees and take on extra paid work. Some of these offers are tempting, especially when money is tight. But there are only so many hours in a day, and every hour spent elsewhere is an hour your main business does not get.
Owners who try to do everything often find that nothing gets their full attention. Customers wait longer, important tasks slip and the core business stalls. Staying focused does not mean refusing every opportunity. It means judging each one against your main goals and accepting only those that clearly support them.
How to Protect Your Focus
- Write down the three most important goals for your business this year.
- Check new requests against those goals before agreeing.
- Block out time in your calendar for deep work on the business, not just in it.
- Delegate or outsource tasks that others can do well, such as bookkeeping or design.
- Review your week every Friday to see where your time actually went.
Why It Matters
Focus compounds. Small, steady improvements to your product, service and customer experience add up over months and years. When your attention is scattered, those gains never build. Many owners find that the business grows faster once they stop spreading themselves thin.
Interesting Facts
- The CB Insights study found that bad timing and unsustainable unit economics were also common failure causes, problems that a focused owner is more likely to notice early.
- Many owners use a simple priority matrix that sorts tasks by how urgent and how important they are.
- Pivoting to a new direction can work, but CB Insights cites companies that pivoted and still failed to find a viable market.
8. Surround Yourself With Good Advisers
| Attribute | Details |
|---|---|
| Core idea | No owner can be an expert in everything |
| Who to look for | Mentors, an accountant, a lawyer, experienced peers and industry contacts |
| Free help in the US | SCORE, a nonprofit SBA resource partner founded in 1964 |
| SCORE network | More than 10,000 volunteer mentors across all 50 states and US territories |
| Benefit | Avoid expensive mistakes and stay focused on what works |
What It Means
However talented you are, running a business requires knowledge of finance, law, tax, marketing, hiring, technology and much more. Nobody masters all of it at once. The worst thing an owner can do is stop learning. Surrounding yourself with experienced advisers means you can borrow their knowledge and avoid mistakes they have already made.
Free and low-cost help is often closer than people think. In the United States, SCORE has offered volunteer business mentoring since 1964, when SBA Administrator Eugene P. Foley launched it with 2,000 members. Today it describes itself as the country's largest network of volunteer business mentors, with more than 10,000 volunteers, and says it has supported more than 17 million entrepreneurs. Many other countries have similar government-backed programmes, chambers of commerce and industry associations.
Building Your Advisory Circle
- Find an accountant early, ideally before you choose your business structure.
- Use a lawyer to review contracts, leases and partnership agreements before you sign.
- Join a local business group or an online community of owners in your industry.
- Look for a mentor who has run a business similar to yours, a few stages ahead of where you are.
- Consider an informal advisory board of two or three trusted people who meet with you a few times a year.
Why It Matters
Advisers give you something money cannot easily buy: perspective. They can spot risks you are too close to see, challenge unrealistic plans and point you toward strategies that have worked elsewhere. The SBA itself recommends talking to mentors, vendors and service providers when estimating costs for a new business.
Interesting Facts
- SCORE was originally a group of retired executives, but the organisation says that today about half of its volunteers are still actively working.
- SCORE began offering email counselling in 1996 and moved to fully virtual mentoring at the start of the COVID-19 pandemic.
- According to a 2024 SCORE press release, its volunteers provided 4.5 million hours of mentoring and education in the previous year.
9. Take Care of Yourself
| Attribute | Details |
|---|---|
| Core idea | The owner's health is one of the business's most important assets |
| Common risks | Long hours, poor sleep, little exercise and constant stress |
| Burnout | Recognised by the WHO in 2019 as an occupational phenomenon in ICD-11 |
| Basic habits | Sleep, movement, regular meals and real time off |
| Business benefit | Clearer thinking, better decisions and fewer forced absences |
What It Means
Looking after yourself can sound like an odd business tip, but it makes a lot of sense. Starting a business usually means long days, late nights and weekends spent catching up. When missed sleep, skipped workouts and takeaway dinners pile up, the result can be exhaustion or illness, which means medical costs and time away from a business that may depend entirely on you.
In 2019 the World Health Organization included burnout in its International Classification of Diseases (ICD-11) as an occupational phenomenon, describing it as the result of chronic workplace stress that has not been successfully managed. Business owners, who often carry financial risk and responsibility for staff, are not immune.
Healthy Habits for Owners
- Protect your sleep as carefully as you protect your cash flow.
- Schedule exercise like a meeting, even if it is a short daily walk.
- Take at least one full day a week away from work whenever possible.
- Build systems and train others so the business can run for a few days without you.
- Talk to friends, family, peers or a professional when stress builds up.
Why It Matters
Tired people make worse decisions. They react instead of planning, overlook warning signs and treat customers and staff with less patience. Staying healthy keeps your judgement sharp, which is good for you and good for the business.
Interesting Facts
- The WHO is clear that burnout in ICD-11 refers specifically to the work context, not to other areas of life.
- Many owners find that taking proper breaks improves their creativity and problem solving.
- Succession and contingency plans protect a business if the owner is suddenly unable to work.
10. Know When to Cut Your Losses
| Attribute | Details |
|---|---|
| Core idea | Not every venture will work, and that is not a personal failure |
| Psychological trap | The sunk cost effect, continuing because you have already invested so much |
| Key research | Hal Arkes and Catherine Blumer, The Psychology of Sunk Cost, 1985 |
| Better question | Would I invest in this today, knowing what I know now? |
| Next step | Close or change direction, learn the lessons and start again stronger |
What It Means
Some business ideas do not work, however hard the owner tries. Markets change, timing is wrong, costs rise or customers simply do not want the product enough. It is painful to admit, but continuing to pour money and years into a venture that is clearly failing only makes the eventual loss bigger.
Psychologists call one of the forces at work the sunk cost effect. In a well-known 1985 paper, Hal Arkes and Catherine Blumer showed that people tend to keep investing in something once they have already spent money, effort or time on it, even when the future outlook is poor. The money already spent is gone either way. The only question that matters is whether the next investment makes sense.
How to Decide
- Set clear milestones in advance, such as a sales target or a date, and review honestly when you reach them.
- Ask a trusted adviser for an outside opinion.
- Look at whether the problem is the whole business or one product, location or channel that could be closed on its own.
- Consider alternatives such as selling the business, merging or changing direction.
- If you do close, do it properly, paying what you owe where possible and keeping good relationships.
Why It Matters
Closing a business is not the end of an entrepreneurial career. Many successful founders failed before they succeeded, and the lessons from one venture often shape the next. The CB Insights study found that nearly a quarter of the failed startups it examined had gone more than three years without new funding before officially shutting down, a sign that ending sooner might have saved time and money.
Interesting Facts
- The sunk cost effect is sometimes called the Concorde fallacy, after the supersonic airliner that governments kept funding despite heavy losses.
- Arkes and Blumer's paper was published in the journal Organizational Behavior and Human Decision Processes.
- According to the SBA Office of Advocacy, more than half of new US establishments close before reaching five years, so closure is a common experience, not a rare one.
Business Owner Essentials Compared
| Area | Essentials | First Step This Week |
|---|---|---|
| Money | Cash flow, careful spending, safety margin | Build a simple 3-month cash flow forecast |
| Information | Measuring results | Calculate your break-even point |
| Customers | Sales and marketing, pitching | Write and practise a 30-second pitch |
| Time and people | Focus, advisers | List your top three goals and find one mentor |
| Yourself | Health, honest decisions | Schedule one full day off and set a review milestone |
Frequently Asked Questions
What is the most important thing to know as a business owner?
Most experts would point to cash flow. A business can be profitable on paper and still fail if it cannot pay its bills on time. Running out of capital was cited in 70 percent of the recent startup shutdowns analysed by CB Insights, so forecasting cash, collecting payments promptly and keeping a buffer should be a top priority from day one.
How many new businesses survive five years?
According to the SBA Office of Advocacy, an average of 49.2 percent of new US employer establishments survived five years between 1994 and 2021. The two-year survival rate was 67.9 percent and the ten-year rate was 33.8 percent. Survival odds improve with age, as more than two-thirds of businesses that reach five years also reach ten.
Why do most small businesses fail?
There is rarely one cause. Running out of cash is usually the final blow, but the root problems are often weak demand for the product, poor timing, costs that are too high for the price charged, or a lack of planning. Careful market research, conservative financial forecasts and regular tracking of results help owners spot these problems early.
Where can a new business owner find a mentor?
Good places to start include local chambers of commerce, industry associations, business incubators and owners you already know. In the United States, SCORE, a nonprofit resource partner of the SBA, has offered free volunteer mentoring since 1964 and has more than 10,000 mentors. Many other countries run similar government-backed or nonprofit mentoring schemes for small firms.
How do I calculate my break-even point?
Divide your fixed costs by the difference between your selling price per unit and your variable cost per unit. The result is the number of units you must sell to cover all your costs. For example, if fixed costs are 5,000 a month and each sale contributes 25 after variable costs, you need 200 sales a month to break even.
How can business owners avoid burnout?
Protect your sleep, build regular exercise and real time off into your schedule, and delegate tasks others can handle. Creating simple systems so the business can run without you for a few days also reduces pressure. The WHO describes burnout as the result of chronic workplace stress that has not been managed, so addressing stress early is key.
When should you close a business?
Consider closing when the business repeatedly misses clear milestones, keeps needing personal money to cover routine costs and shows no realistic path to profit. Ask whether you would invest in it today if you were starting fresh. If the honest answer is no, closing or changing direction is often wiser than continuing because of money already spent.
Conclusion
Owning a business is tough, but it becomes far more manageable when you understand the essentials. Watch your cash flow, give every expense a purpose and plan with a safety margin. Measure your results, put customers and sales at the centre of everything and keep a clear pitch ready. Protect your focus, learn from experienced advisers, look after your health and be honest enough to cut your losses when something is not working.
None of these lessons guarantees success, and many of them are learned through trial and error. That is normal. The owners who last are usually not the ones who never make mistakes, but the ones who notice them early, adjust quickly and keep learning. For more inspiration, explore Finepedia's Entrepreneurship section and our profiles of influential business leaders.
- U.S. Small Business Administration, Office of Advocacy: Frequently Asked Questions About Small Business, July 2024
- U.S. Bureau of Labor Statistics: 1-year survival rates for new business establishments by year and location, The Economics Daily, March 2024
- U.S. Small Business Administration: Plan your business, including Calculate your startup costs and break-even analysis guidance
- CB Insights: The top 9 reasons startups fail, March 2026
- SCORE: About SCORE and SCORE Celebrates 60 Years of Serving America's Small Businesses, September 2024
- World Health Organization: Burn-out an occupational phenomenon, International Classification of Diseases, May 2019
- Arkes, H. R. and Blumer, C. (1985). The Psychology of Sunk Cost. Organizational Behavior and Human Decision Processes, 35(1), 124-140
Log in with